Uday Kotak has proposed a dedicated committee to examine India’s rising gold imports, with the country’s FY27 gold import bill potentially reaching dollar 88–90 billion.
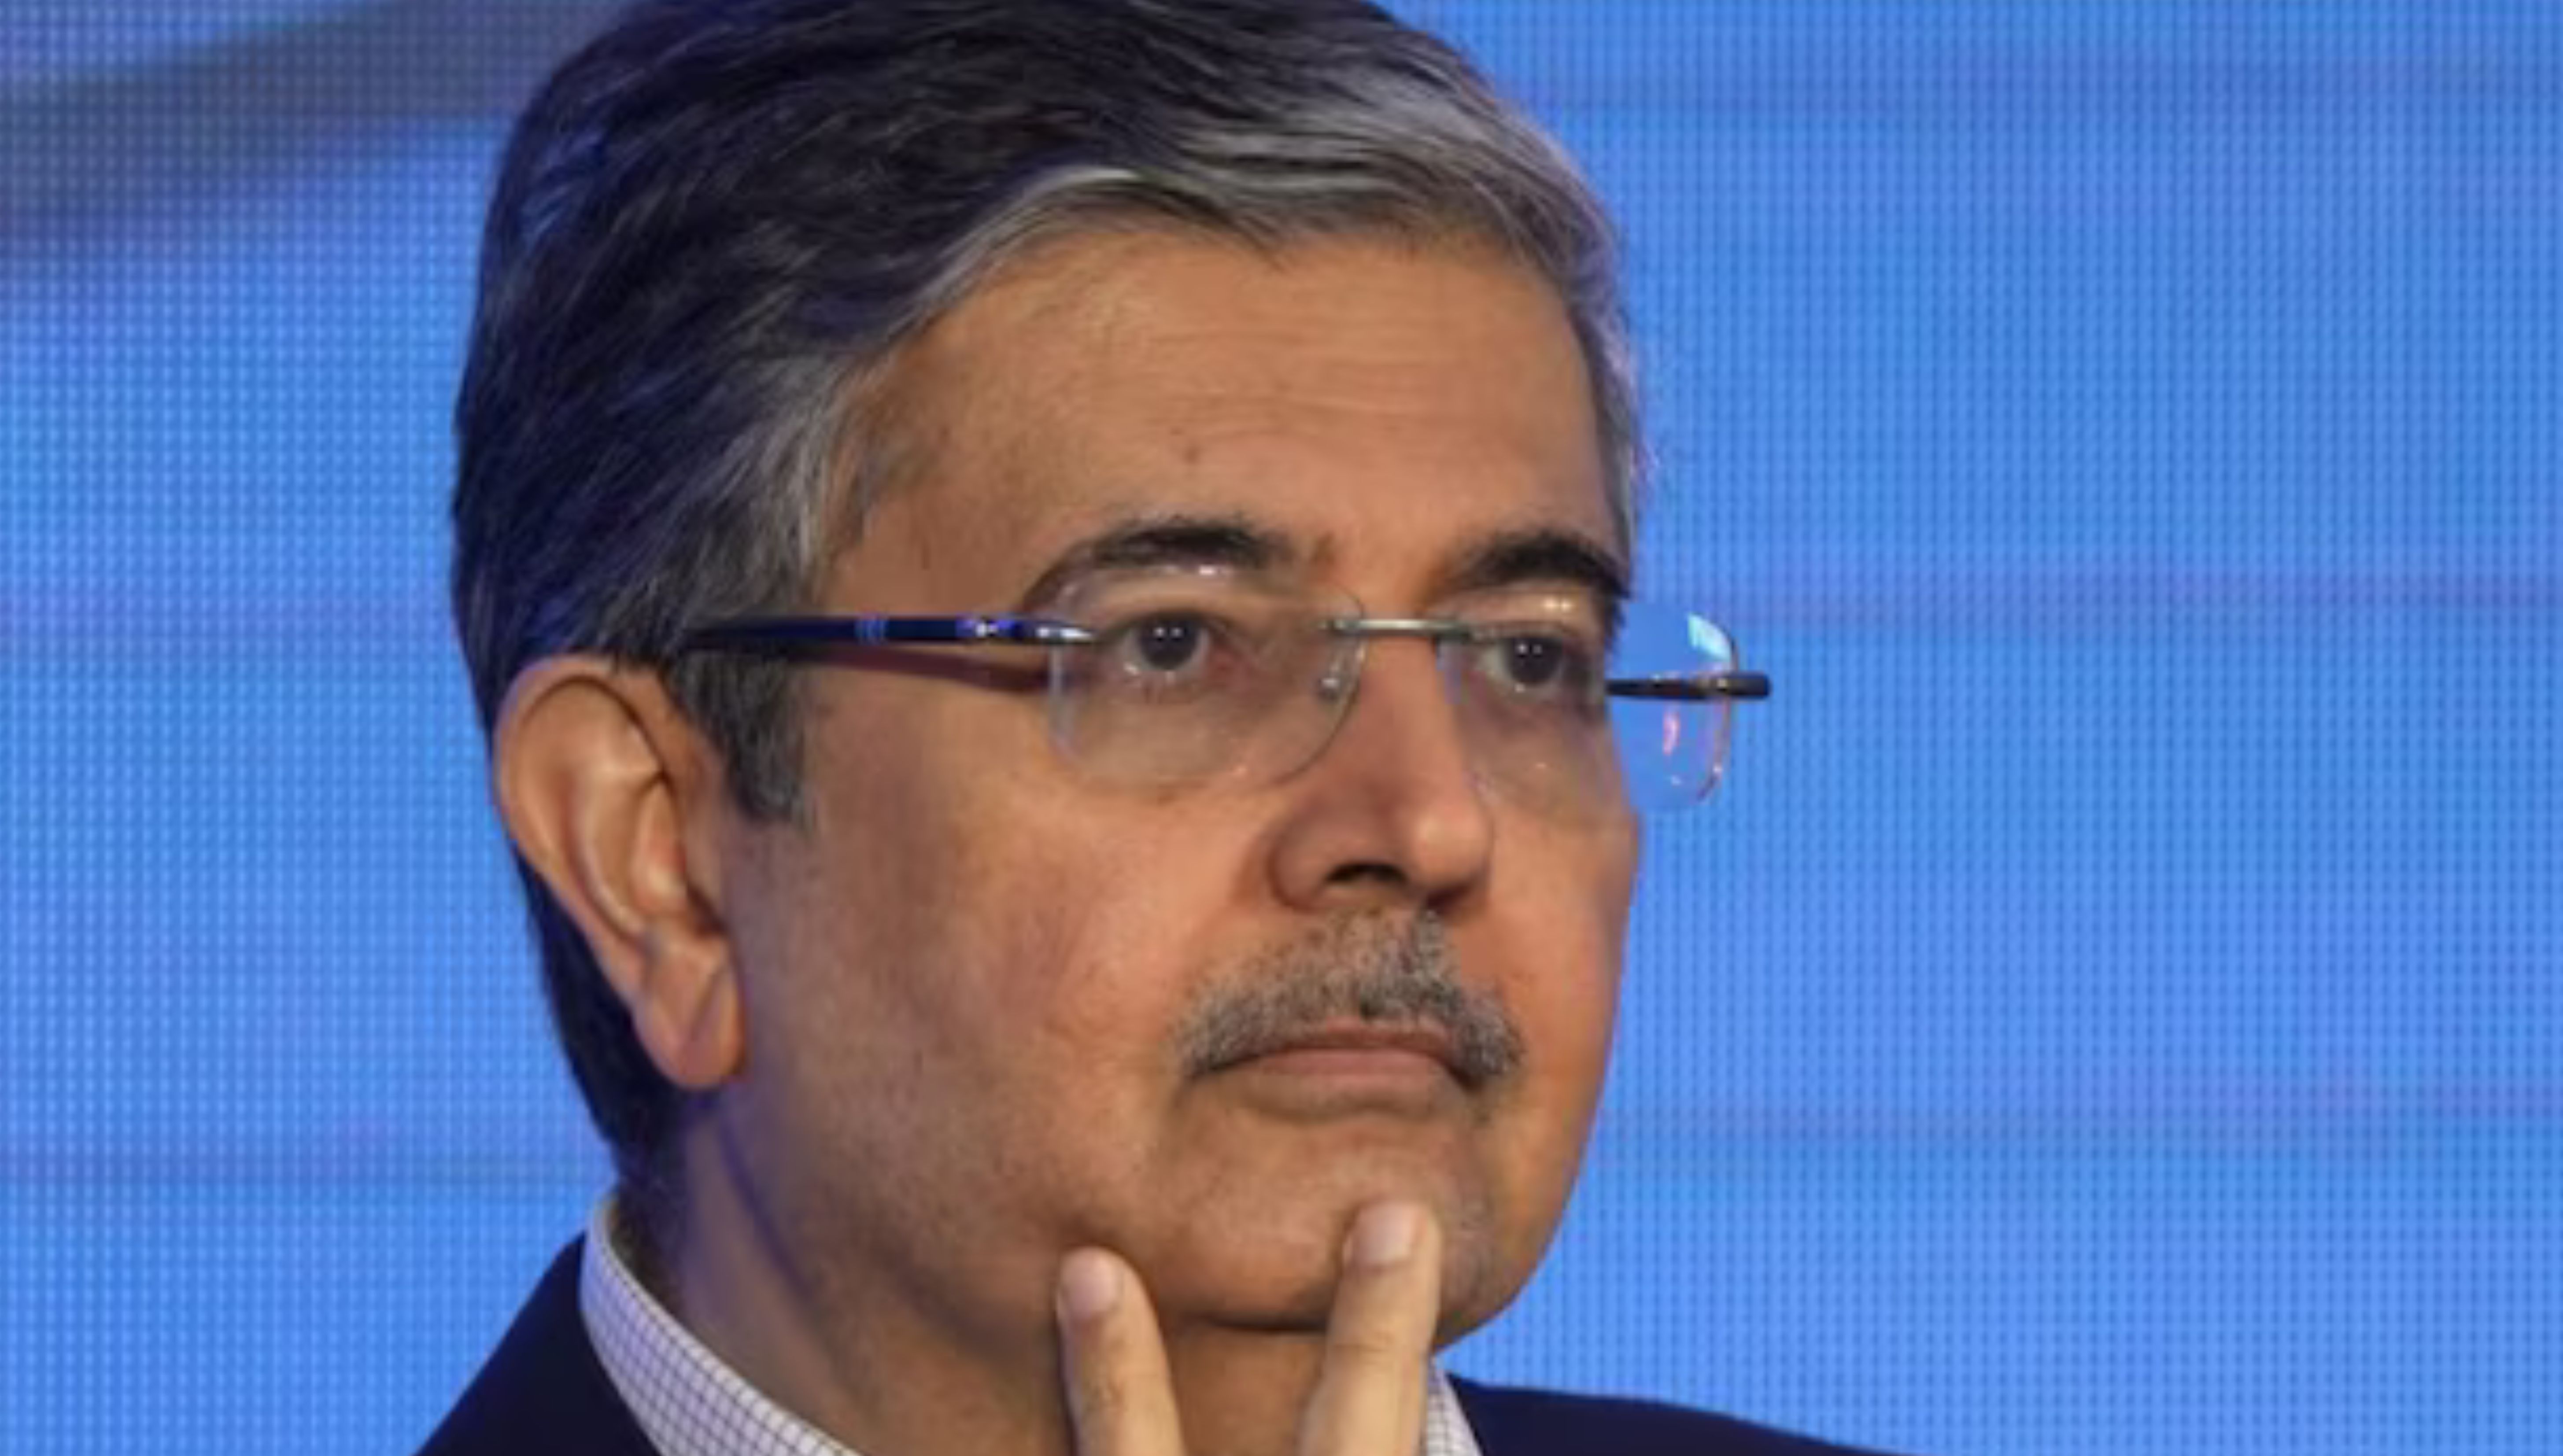
Uday Kotak has called for a dedicated committee to examine India’s rising gold imports, warning that the country’s gross gold import bill could reach dollar 88–90 billion in FY27 and add pressure to the current account.
Speaking at the Conference on Financing India’s Journey Towards Viksit Bharat in New Delhi, Kotak said India’s gold imports stood at about dollar 72 billion in FY26, while the country’s current account deficit was around dollar 25 billion. Excluding gold, India would have recorded a current account surplus, he said.
For FY27, Kotak estimated that the current account deficit could reach around dollar 60 billion, assuming crude oil prices average about dollar 90 a barrel. Against this backdrop, he projected gold imports at dollar 88–90 billion.
Kotak said any policy response should consider both the import burden and continued household demand for gold. He proposed a committee to examine how household gold wealth could be better integrated with the formal economy while taking individual requirements into account.
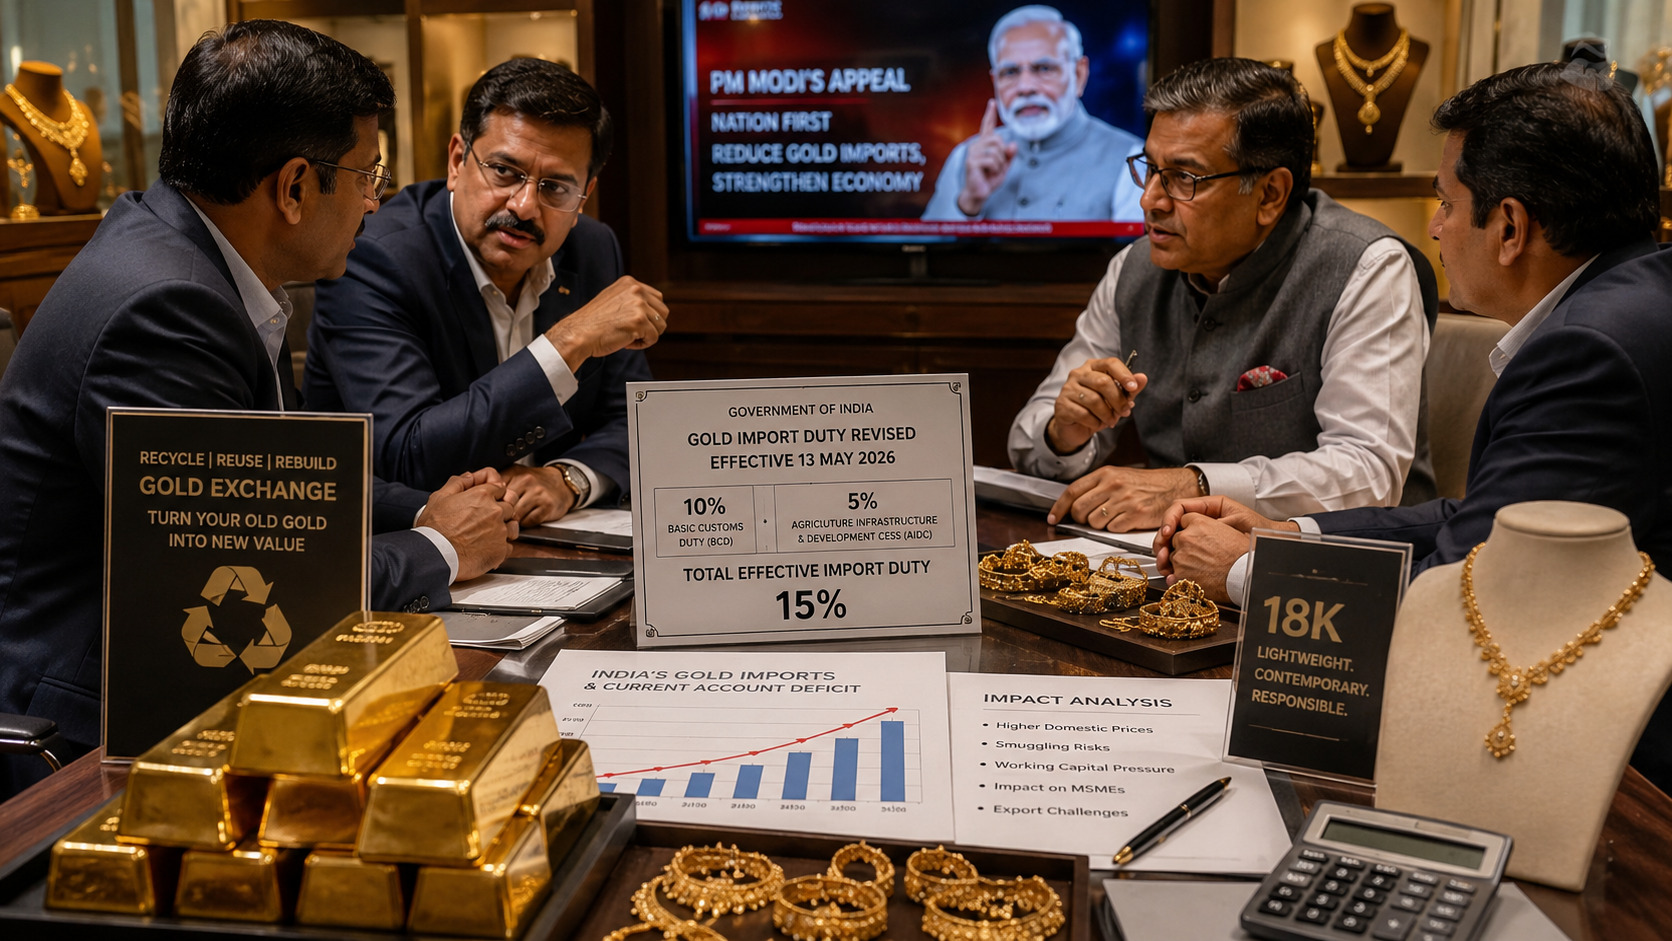
Gold imports had already risen more than 24% to a record dollar 71.98 billion in FY26 from dollar 58 billion in FY25, although import volumes declined 4.76% to 721.03 tonnes. Rising international gold prices were a key factor behind the higher import value.
The issue has direct implications for the jewellery sector, which accounts for a significant share of domestic gold consumption and remains dependent on imported bullion.
Be the first to comment